Your Ventura County real estate agent for VA buyers
An agent who knows VA home loans.
I’m Edgar Limon, a real estate agent and licensed loan officer, born and raised in Oxnard. If you’re on active duty, a veteran, in the Guard or Reserve, or a surviving spouse, I help you buy in Ventura County with a VA home loan, and I know the loan side too.
- Born and raised in Oxnard
- Real estate agent and licensed loan officer
- Hablo español
Edgar Limon, REALTOR®, DRE #02225743, Century 21 Masters · Loan officer, NMLS #2256286 · Not affiliated with the VA
A short video hello, so you know the person behind this page before you call.
Client reviews
In their words, from Google
Each quote is copied word for word from my Google reviews, and … shows where words were left out. Read the full reviews
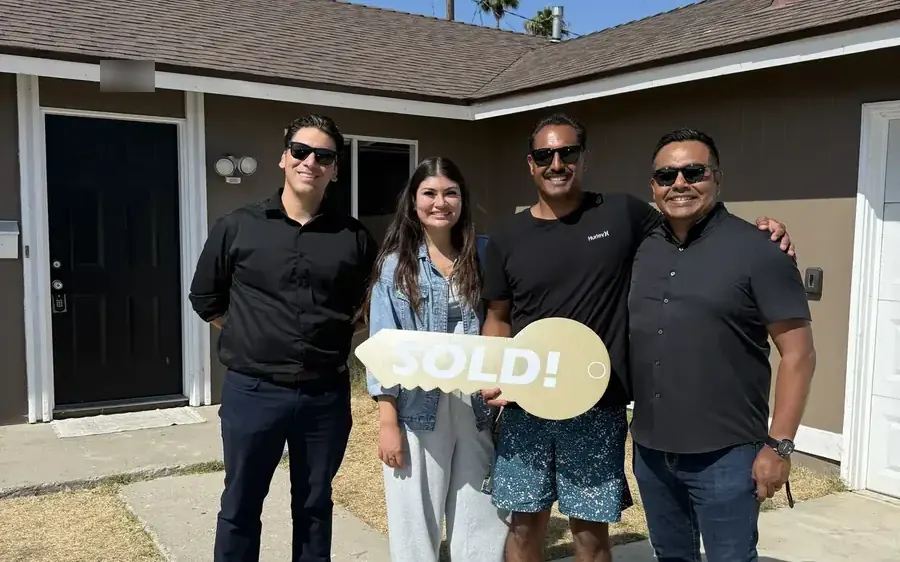
“… They were especially helpful with navigating the VA loan process, answering all of our questions, and keeping us informed every step of the way. They were patient, knowledgeable, and genuinely went above and beyond…”
Alejandro & Rosemary
VA buyers, Google review, shortened
“…I enjoyed his transparency, his patience, and his experience and professionalism were on full display throughout the whole buying process… walking me through various paperwork and contingency removals, it was all a pain-free experience…”
Luis G
Google review, shortened
VA home loans in 60 seconds
How a VA home loan works
A VA home loan is a mortgage from a private lender that the U.S. Department of Veterans Affairs partly backs. Here is what that means for you.
-
A private loan VA partly backs
The loan comes from a lender you choose. VA guarantees part of it, which is why the program has features most loans don’t.
-
Flexible down payment rules
Eligible buyers with full entitlement get flexible down payment rules when the price is not above the appraised value. Lenders set their own requirements.
-
No monthly mortgage insurance
VA loans carry no private mortgage insurance and no monthly mortgage insurance premium, a cost many other loans carry.
-
A one-time funding fee
Most VA buyers pay a one-time funding fee, at closing or financed into the loan. Veterans receiving VA disability compensation are exempt.
-
No VA loan limit with full entitlement
As long as you can afford the loan and the appraisal supports the price. Lenders may set their own maximums.
-
You live in the home
You certify that you will live in the home as your primary residence, as a rule within 60 days after closing.
How I help
How I help VA buyers and sellers
I’m dual licensed, on the house side and the loan side, so I can spot issues ahead of time for VA buyers.
Book a free 30-minute call-
Buying with a VA loan
I tour with you in person or by video, point out what a VA appraiser is likely to flag, and write an offer with the VA escape clause and clear repair terms. You choose your lender.
-
Moving here on orders
Coming from another part of the country or from overseas? I help with the transition and give advice on locations based on what you want, from the commute to the kind of home.
-
Selling or renting after orders
Sell, rent it out or let a buyer assume your VA loan: I lay out each option with you, and if you have already reported elsewhere, I handle the sale here by phone and video.
VA home loan questions, answered
1. Is there a Ventura County real estate agent who also knows VA loans?
Yes. I’m Edgar Limon, a real estate agent with Century 21 Masters (CA DRE #02225743) and a licensed loan officer (NMLS #2256286), born and raised in Oxnard. Because I’m dual licensed, I can spot issues ahead of time for VA buyers. I also help buyers relocating from other parts of the country or from overseas with the transition, and give advice on locations based on what they want.
2. How long does a VA pre-approval last?
VA’s lender handbook doesn’t set an expiration date for a pre-approval letter. It limits document age instead: for most VA loans, the credit report and the income and asset verifications can be no more than 120 days old when the note is signed (180 days for new construction). Your lender’s letter shows its own expiration date.
3. Do I need a down payment for a VA loan in Ventura County?
Per VA.gov, it depends on your entitlement and on whether the sales price is higher than the appraised value, and a lender can set its own requirements. A personal quote shows what applies to you. Every loan is subject to credit approval.
4. What credit score do I need for a VA loan?
VA doesn’t set a minimum credit score. Each lender sets its own and also reviews your income and debts.
5. Who is exempt from the VA funding fee?
Veterans receiving VA compensation for a service-connected disability, people eligible for it who receive retirement or active-duty pay instead, surviving spouses receiving DIC, service members with a proposed or memorandum rating before closing, and active-duty Purple Heart recipients. Your Certificate of Eligibility (COE) shows your status.
6. Can BAH count as income for a VA loan?
Yes, when it is verified. VA’s lender handbook lets lenders include BAH in effective income, and the amount changes from one duty station to another. For 2026, an E-5 with dependents at NBVC receives $3,537 in BAH, per DoD.
7. What does the VA appraisal check?
The value, and VA’s minimum property requirements: a home that is safe, structurally sound and sanitary, with a roof that keeps moisture out, working heat and utilities, year-round access and no peeling paint in homes built before 1978. In California VA also requires termite information. The appraisal is not an inspection, so I recommend a home inspection on every purchase.
8. Can I use a VA loan on a condo in Oxnard or Port Hueneme?
Yes, when the condo project is approved by VA, and projects approved by HUD or USDA are generally accepted too. Check VA’s condo report before you write an offer, or send me the complex name. Homes in a planned unit development don’t need project approval.
10. Can I use my VA loan more than once?
Yes. The benefit doesn’t expire. After you sell and pay off the loan, your lender can apply to restore your entitlement, and you may have two VA loans at once if your remaining entitlement covers the new one. A VA loan can also buy a home with up to four units when you live in one of them.
11. Can I get a VA loan after bankruptcy or foreclosure?
It can be possible after a waiting period. VA’s guideline lets a lender disregard a Chapter 7 discharge or a foreclosure more than 2 years before closing, consider 1 to 2 years with re-established credit and a cause beyond your control, and consider a Chapter 13 after 12 months of plan payments with the court’s or trustee’s approval. Many lenders set stricter rules.
12. Can I rent out my home after I PCS?
Generally, yes. VA requires that you intend to live in the home as your home when you close and that you move in within a reasonable time. If orders later move you, renting it out is generally allowed, and a VA streamline refinance (IRRRL) only needs your past occupancy. Talk with a tax professional about capital gains.
13. Can a non-veteran assume my VA loan?
Yes, if the buyer is creditworthy and the servicer approves. An approved assumption releases you from liability, but your entitlement stays tied to the loan unless the buyer is an eligible veteran who substitutes their own.
Distance to NBVC
Homes near Naval Base Ventura County
Port Hueneme and Point Mugu sit on the coast south of Oxnard. Pick a city to see its homes for sale, then test the drive to your gate at the hours you would commute.
 Ventura
 Oxnard
 Camarillo
 Port Hueneme
 Somis
 Moorpark
 Simi Valley
 Thousand Oaks
 Newbury Park
 Oak Park
 Westlake Village
 Santa Paula
 Fillmore
 Piru
 Ojai
Your next step
Let’s talk about your VA purchase
Send your orders, your timeline or your questions. Book a free 30-minute call and I’ll walk you through the house side and the loan side.
Get a loan quote · Get the VA checklist · Search homes near NBVC
Licensing and disclosures
Edgar Limon, REALTOR®, CA DRE #02225743, with Century 21 Masters. Each office is independently owned and operated. Mortgage loan originator, NMLS #2256286, with 21st Century Lending, NMLS #241835, a division of Full Realty Services, Inc. Licensed by the Department of Financial Protection and Innovation under the California Residential Mortgage Lending Act and California Financing Law. Loans made or arranged pursuant to a California Financing Law license. Verify licenses at NMLS Consumer Access.
Century 21 Masters and 21st Century Lending are affiliated companies. You are not required to use 21st Century Lending, or any particular lender, as a condition of working with me, and if I act as both your agent and your loan officer, I disclose both roles and how I am paid to you in writing. I am not affiliated with or endorsed by the U.S. Department of Veterans Affairs, HUD, USDA or any government agency.
This page is general information, not a commitment to lend, and not tax or legal advice. All loans are subject to credit approval, eligibility, appraisal and property requirements. Programs can change. Equal Housing Opportunity. Equal Housing Lender.
Broker: Century 21 Masters, CA DRE #01849354.